
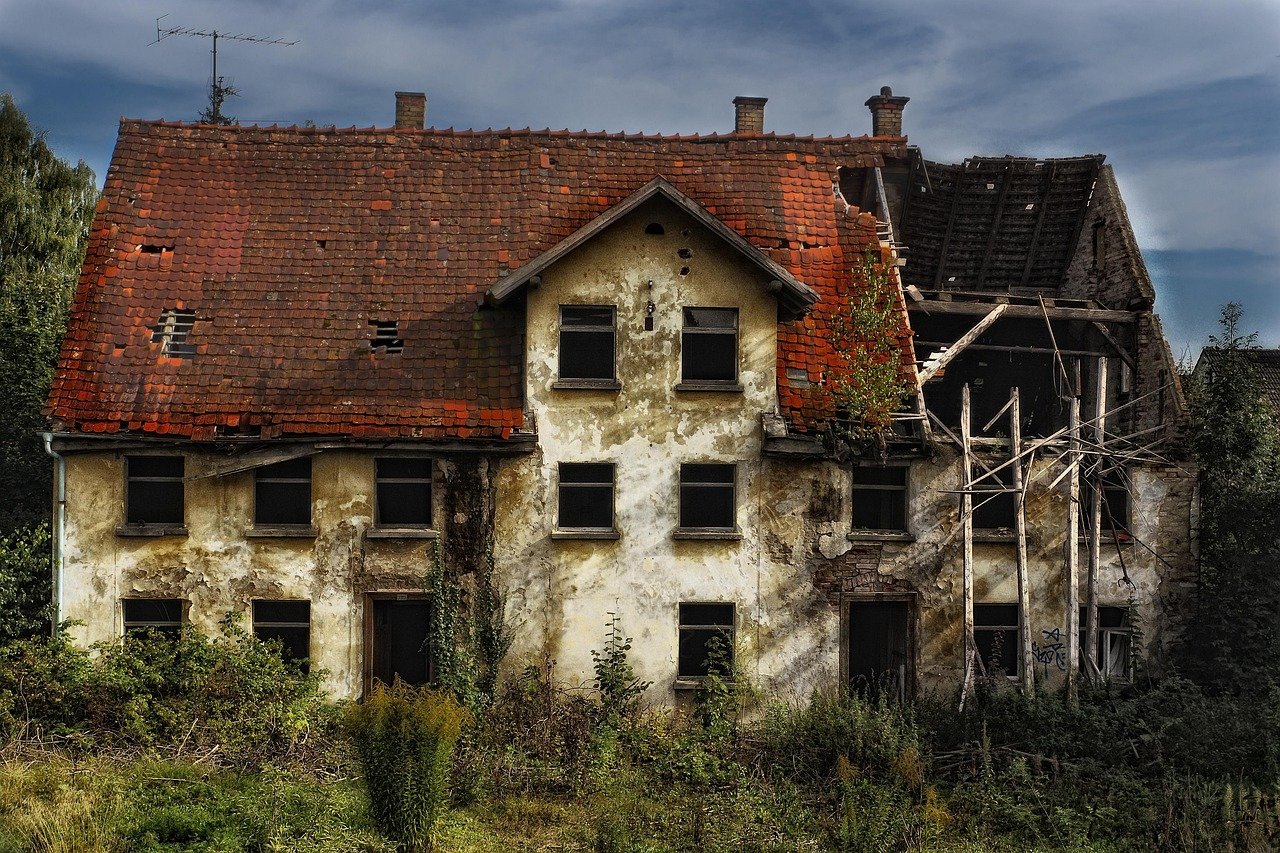
What if the charming old house with the crooked porch and the “great bones” could quietly cost you more than you ever imagined? That is the fear behind the phrase money pit, and it is a fear with real numbers behind it. The term describes a place, project, or venture that keeps swallowing money without giving much back. Most often, it means a home that needs endless repairs. But the same logic applies to a failing business line, a used car, or a boat that spends more time in the shop than on the water.
This article looks at where the phrase comes from, why homes become money pits, how buyers can spot the warning signs, and how the idea shows up in business and personal finance. It also covers the practical steps that actually work, the mistakes people make, and the questions buyers ask most.
Where the phrase “money pit” comes from
The idiom is informal, and no single official dictionary definition or first-use date exists. It entered everyday American English largely through popular culture. The 1986 comedy The Money Pit, starring Tom Hanks and Shelley Long, follows a couple whose dream house collapses around them, literally and financially. The film is widely credited with pushing the phrase into common speech.
It was not the first story of its kind. The 1948 comedy Mr. Blandings Builds His Dream House has almost the same premise: a city couple buys a crumbling country home and watches the budget spiral. Both films work because the situation is so recognizable. Anyone who has owned an older house knows the feeling of a small repair turning into a large one.
What makes a house a money pit
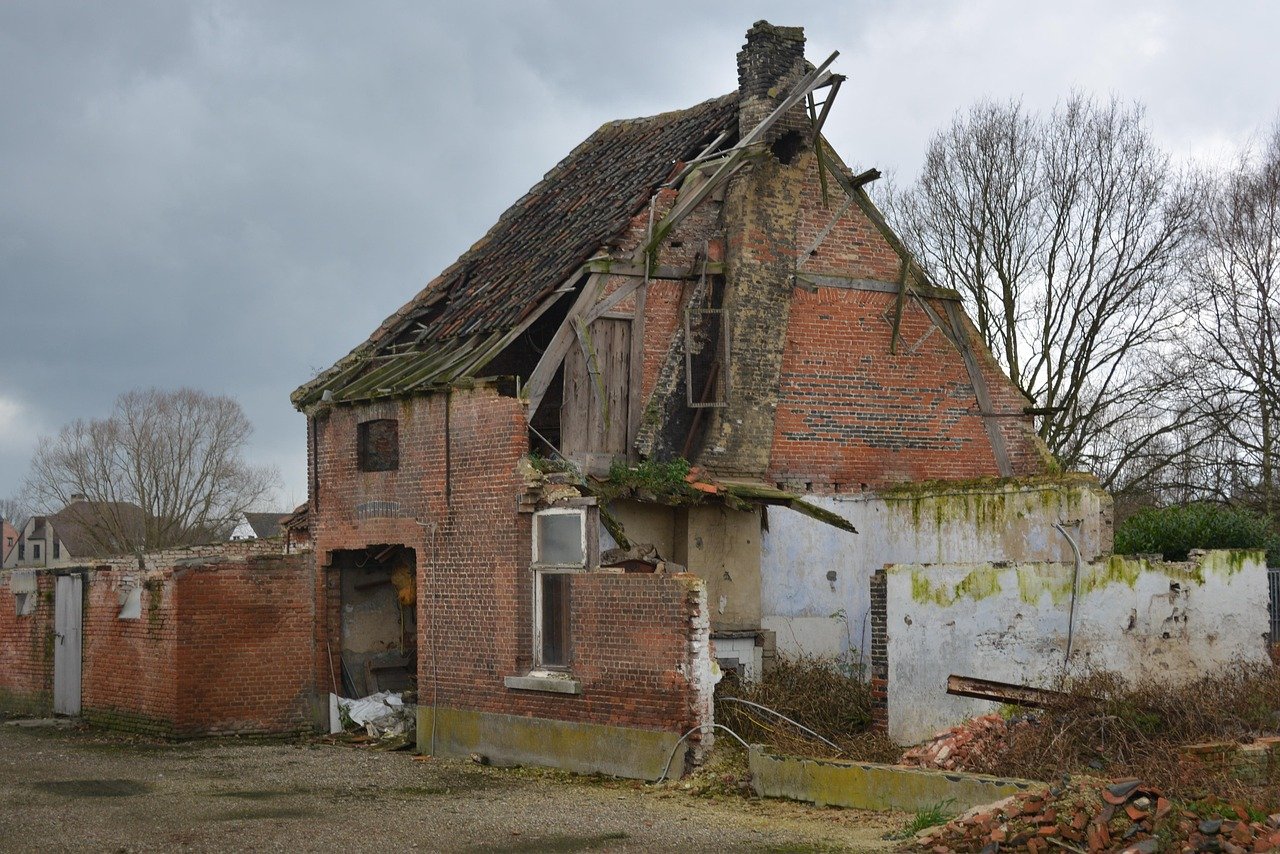
A money pit is not simply an expensive house. It is a house where costs keep coming and value does not keep up. The difference matters. A kitchen remodel can be expensive and still add value. A failing foundation, by contrast, drains cash and may scare off future buyers.
Several factors push a home toward money-pit territory:
- Deferred maintenance. When owners skip roof repairs, gutters, and paint for years, small problems become structural ones.
- Hidden defects. Water damage, mold, faulty wiring, and foundation cracks often sit out of sight until they are expensive.
- Age of the housing stock. Older homes generally need more upkeep. A large share of the U.S. housing stock was built before 1980, which is the factual basis for much of the worry.
- Renovation scope creep. A “small” bathroom update turns into new plumbing, new tile, and a new subfloor.
- Poor workmanship. Cheap fixes by previous owners can cost more to undo than to do properly the first time.
The spending is measurable. The U.S. Census Bureau’s American Housing Survey collects data on homeowners’ repair and improvement spending, and it is the standard public dataset for understanding how much households actually put into their homes each year.
The real cost of owning an older home
Buyers often budget for the mortgage and forget everything else. A useful rule of thumb is to set aside 1% to 3% of a home’s value each year for maintenance and repairs. On a $400,000 house, that is $4,000 to $12,000 annually. For an older home with known issues, the figure can run higher. (National Association of Home Builders)
| Home age | Typical upkeep profile | Budget pressure |
|---|---|---|
| New build (0-10 years) | Minor fixes, warranty coverage | Low to moderate |
| 10-30 years | Roof, HVAC, water heater replacements | Moderate |
| 30-60 years | Plumbing, electrical, windows, siding | High |
| 60+ years | Foundation, structural, full systems | Very high |
These are general patterns, not guarantees. A well-maintained 1920s house can cost less to run than a neglected 1990s one. Maintenance history matters more than the year on the deed.
How to spot a money pit before you buy
The single best defense is a thorough home inspection. In the U.S., the relevant professional standard is the American Society of Home Inspectors’ Standards of Practice, which defines what a inspector examines and reports. Knowing what the standard covers helps buyers ask better questions and read the report with clear eyes.
Practical steps that work:
- Hire an inspector who specializes in older homes. A generalist may miss subtle signs of structural movement or outdated wiring.
- Attend the inspection in person. Walking the house with the inspector teaches more than any written report.
- Get specialist inspections for red flags. Foundation, sewer scope, roof, and mold assessments cost a few hundred dollars each and can save tens of thousands.
- Request maintenance records. A seller who kept receipts and service logs is a seller who likely cared for the house.
- Read disclosure statements carefully. Many states require sellers to disclose known defects. Compare disclosures against the inspection findings.
- Get contractor quotes before closing. Turn inspection findings into real numbers, then negotiate or walk away.
Common mistakes buyers make
The most common error is falling in love with a house before doing the math. Emotional attachment makes buyers discount inspection findings and underestimate repair costs. A second mistake is treating a low purchase price as a bargain without adding the cost of needed repairs. A third is skipping specialist inspections to save a few hundred dollars, only to discover a $20,000 foundation problem later.
Another frequent slip: trusting a verbal “it’s an easy fix” from the seller or agent. Get it in writing, with a quote from a licensed contractor. If the fix is truly easy, the seller can price it into the deal.
Money pits beyond housing
The phrase travels well. In business, a money pit is any venture that consumes cash without producing a return. A product line that never turns a profit, a subsidiary that needs constant funding, or a marketing channel that spends more than it earns all qualify. The idea overlaps with the accounting concept of a cash cow in reverse: instead of generating steady cash, the venture absorbs it.
This matters for anyone evaluating a new income stream. Before committing money to a project, it helps to understand how the underlying business actually earns revenue. A guide on how do ai companies make money explains the models behind one of the fastest-growing sectors, which is useful context when judging whether a venture has a real path to profit or is just burning cash.
The same logic applies to side projects. Plenty of people sink money into tools, courses, and subscriptions before earning a dollar. A practical guide on how to make money with ai walks through realistic paths, and it is worth reading before funding an idea that could quietly become a money pit of its own.
When a money pit becomes a security risk
Some money pits are expensive and dangerous. A home with outdated wiring, a failing roof, or a compromised smart-home setup can expose owners to real harm. Security spending therefore deserves the same scrutiny as any other repair budget.
Understanding where the money actually goes helps owners avoid overpaying for protection that does not deliver. A breakdown of identity threat detection really costs where money goes shows how budgets get allocated, which is useful when deciding whether a security upgrade is a genuine fix or just another drain.
The same principle applies to business security. Companies that buy tools without understanding the threat landscape often waste money on features they never use. A look at threat intelligence actually costs 2025 where money goes explains the cost structure, helping buyers separate real value from marketing.
Money pits in personal finance and fraud
Not every money pit is a building. Some are scams. The gift card scam is a classic example: a caller claims to be from the government or a utility, demands payment in gift cards, and disappears with the codes. Victims rarely recover the money, which makes this one of the purest money pits in consumer life. A detailed explanation of gift card scam works victims rarely get their money back covers how the scheme operates and why recovery is so difficult.
Currency and payment technology also create new ways to lose money. Central bank digital currencies are being explored by many governments, and understanding the basics helps consumers avoid confusion-driven losses. An overview of cbdc digital currency central bank money going digital explains what these currencies are and how they differ from ordinary bank deposits.
How to avoid creating a money pit
Prevention beats repair. Whether the project is a house, a business, or a personal purchase, a few habits keep costs from spiraling:
- Set a hard budget with a contingency. Add 15% to 20% for surprises. There are always surprises.
- Get three quotes. For any major work, competition reveals the real market price.
- Prioritize structural and safety issues. Fix the roof before the wallpaper.
- Track spending monthly. Small leaks add up faster than big ones.
- Know when to walk away. A sunk cost is not a reason to keep spending.
The last point is the hardest. People keep pouring money into failing projects because they have already invested so much. But the money already spent is gone. The only question that matters is whether the next dollar will return more than it costs.
Conclusion
A money pit is less about a specific object and more about a pattern: money goes in, value does not come out. The phrase stuck because the pattern is so common, from crumbling houses to failing ventures to clever scams. The good news is that money pits are usually visible in advance to anyone willing to look. Inspections, written quotes, honest budgets, and a willingness to walk away do most of the work. The buyers who get hurt are rarely the ones who lacked information. They are the ones who let hope override the numbers. Look closely, ask hard questions, and price the repairs before you sign. That is how a dream house stays a home instead of becoming a warning story.
Frequently asked questions
What does money pit mean?
A money pit is a place, project, or purchase that keeps absorbing money without returning value. It is most often used for houses that need constant repairs, but it also describes failing businesses, unreliable vehicles, and ventures that never turn a profit.
Why is an older house more likely to become a money pit?
Older homes generally need more maintenance because systems like roofs, plumbing, wiring, and foundations wear out over time. A large share of the U.S. housing stock was built before 1980, so many buyers face exactly this risk. Maintenance history matters as much as age.
How much should I budget for home repairs?
A common guideline is 1% to 3% of the home’s value per year for maintenance and repairs. On a $400,000 house, that is $4,000 to $12,000 annually. Older homes with known issues often need more, so get contractor quotes before closing.
Can a home inspection prevent a money pit?
No inspection can catch everything, but a thorough one catches most major issues. Hire an inspector experienced with older homes, attend in person, and order specialist assessments for foundation, sewer, roof, or mold concerns. The cost is small compared with the repairs it can reveal.
Is a money pit always about real estate?
No. The phrase applies to any venture that drains cash. In business, a product line or subsidiary that never earns a return is a money pit. In personal finance, scams such as gift card fraud are money pits because victims rarely recover their money.
How do I know when to walk away from a project?
Walk away when the next dollar is unlikely to return more than it costs. Money already spent is gone and should not drive the decision. Set a budget with contingency, track spending monthly, and treat the decision as a fresh choice each time.



