A dealership can help you compare financing, value a trade-in, and arrange a test drive, while you review each part of the deal on its own. If you are shopping for a car dealer that can support your needs today, start by deciding what fits your budget and daily routine. A clear plan can make each choice easier to review.
Ask for written terms and take time to read them. The monthly payment matters, but it does not show the full cost of a vehicle or loan. Check the price, financing terms, trade-in offer, and fees as separate parts of the deal. That gives you a clearer view of what you are agreeing to, with fewer surprises after the paperwork is signed.
Bring your budget and the vehicle you want to replace into the conversation before agreeing to any terms.
Key Takeaways
- Review the full loan cost, not just its monthly payment.
- Compare dealership financing with offers from other lenders.
- Gather identity, income, and housing details before applying.
- Use online trade-in estimates as starting points, not final offers.
- Ask for an itemized out-the-door price before you agree.
- Read the warranty and any exchange policy in writing.
How Can a Car Dealer Help You Finance a Vehicle?
A car dealer can arrange financing through a lender, but you can compare that offer with a bank, credit union, or online lender before signing. APR means annual percentage rate, the annualized cost of borrowing that helps you compare loan offers beyond their monthly payments.
Compare the APR, loan term, amount financed, and total paid, not the monthly payment alone. A lower payment can come from borrowing for more months, which may raise the total interest you pay.
The Truth in Lending Act requires disclosure of APR and finance charges for covered credit transactions. The Consumer Financial Protection Bureau explains key auto loan terms, including how APR helps you assess borrowing costs.
Compare dealership financing with outside offers
A dealership may send your application to lenders and present the offers it receives. A bank or credit union can give you a preapproval directly, while an online lender may let you apply through its website.
These routes can offer different rates, loan terms, and conditions. A preapproval can give you a useful comparison point, though the final loan offer may depend on the vehicle and completed application.
Review each offer for the same vehicle price and amount financed. If one lender uses a different term or down payment, ask for a version that matches the other offers.
| Option | Who provides the offer | What to compare | How to use it |
|---|---|---|---|
| Dealership-arranged financing | Lenders through the dealership | APR, term, amount financed, total paid | Compare it with direct offers |
| Bank or credit union preapproval | Your bank or credit union | APR, term, fees, conditions | Use it as a baseline offer |
| Online lender preapproval | An online lender | APR, term, amount, total paid | Check its terms against other offers |
Read the full cost of the loan
Auto loans are commonly offered for 36-72 months. A longer term can lower each payment, but it can increase total interest and the time you risk owing more than the vehicle is worth.
Check the amount financed and total amount payable in the loan disclosures. These figures help you see the cost beyond the vehicle’s listed price.
Compare the APR and total amount payable on the same loan amount and term before choosing an offer.
A loan can appear easier to manage when the payment is smaller. Check how many payments you will make and what you will pay across the full term.
What Should You Prepare Before Applying for an Auto Loan?
Gathering your identity, income, and housing details before you apply can make a loan application easier to complete. Good preparation can also help you avoid delays if a lender needs to confirm a detail.
Lenders may review your credit information and ask for personal details about your identity, income, and residence. The three nationwide credit reporting companies are Equifax, Experian, and TransUnion.
Before you begin, check what the lender needs and gather relevant records. A lender may request the following items:
- Social Security number
- Valid driver’s license
- Recent pay stub or other income verification
- Homeownership or renter documents
- Relevant documents for a co-applicant or cosigner
The lender may ask about your housing costs or how long you have lived at your current address. Answer each field carefully, since errors can slow the application or require a correction.
If someone applies with you, ask which details and records the lender needs from that person. A co-applicant or cosigner may need to provide information directly through the application process.
Online forms can be useful, but they involve sensitive personal information. Check the full web address and confirm the business through contact details you find independently. HTTPS alone does not prove that a website is genuine.
Use safer online habits when sending records from a phone or computer, and avoid links in unexpected messages. You can review steps for protecting your smartphone from malware before handling documents on your device.
Be cautious if an application page asks for information that does not fit the loan process. For a closer look at warning signs, read how to recognize a fake website.
Submit sensitive documents only through the dealership’s secure application channel.
How Do You Estimate Your Trade-In Value?
A useful trade-in estimate starts with the exact vehicle, its mileage, its condition, and its history. Small differences in trim or options can affect how a dealership values the vehicle.
Use the vehicle identification number, or VIN, to identify the exact vehicle before checking estimates. Most vehicles made since model year 1981 use a 17-character VIN.
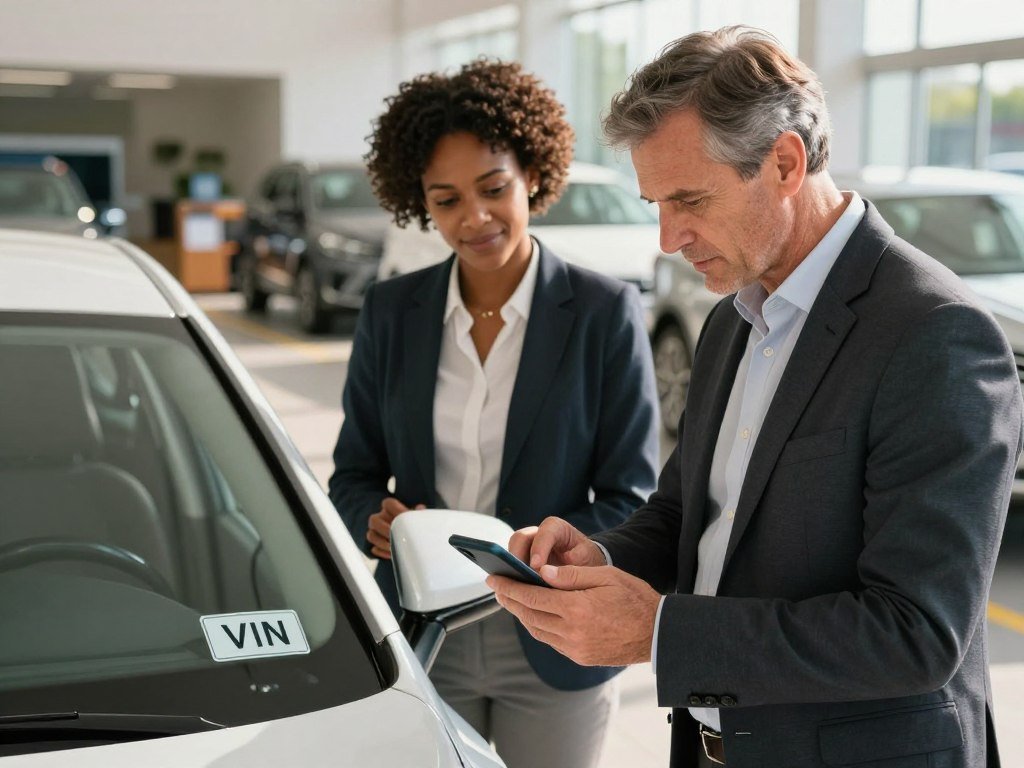
Year, make, model, trim, mileage, condition, options, and vehicle history can all affect an appraisal. Kelley Blue Book and Edmunds provide estimates that can help you compare likely values.
Gather these details before you review an online estimate:
- Year, make, and model
- Trim and options
- Mileage
- Condition
- Accident or service history
Use the VIN on the dashboard or driver-side door area to help identify your exact version. Then compare estimates for the same trim and similar condition, rather than choosing a number from a different model.
Be accurate about wear, damage, and features when entering details. An estimate based on incorrect mileage or missing options may not reflect the vehicle you bring to the dealership.
Online tools provide a comparison point, not a binding trade-in offer. A dealership may change its offer after inspecting the vehicle and checking its documents.
Keep service records and details about past repairs nearby when you discuss the vehicle. Clear information can help explain its condition, even though the final offer depends on the inspection.
Treat any estimate as conditional until the dealership inspects the vehicle and confirms its title details.
Should You Trade In Your Vehicle or Sell It Privately?
Trading in is usually the simpler route when you want to handle the sale and the next purchase together, while a private sale puts more tasks on you. Convenience can matter when you need to replace your vehicle on a set schedule.
A trade-in combines the vehicle sale with your next purchase, while a private sale requires you to manage the sale yourself. The right choice depends on how much time you want to spend and how you plan to handle the proceeds.
With a private sale, you create the listing, answer buyer questions, arrange viewings, handle payment, and complete transfer paperwork. An online instant-offer service can provide another route, but its buyer and process depend on the service.
The Federal Trade Commission advises negotiating the next vehicle’s price separately from the trade-in. That makes it easier to assess each value without mixing the figures.
| Route | Who buys the vehicle | Work the seller handles | How it fits the next purchase |
|---|---|---|---|
| Dealership trade-in | Dealership | Share details and transfer the vehicle | Can be handled with the purchase |
| Private sale | Individual buyer | Listing, messages, payment, transfer | Sale proceeds are handled separately |
| Online instant-offer service | Service or its buyer | Submit details and complete its process | Offer can be separate from the purchase |
If you still owe money, compare the lender’s payoff with the trade-in offer. Trade-in equity equals the offer minus the payoff amount.
If the payoff is higher than the offer, the difference is negative equity. You may pay that amount separately or add it to a new loan, which increases the amount financed.
If the offer is higher than the payoff, the remaining equity may reduce the amount you need for your next purchase. Ask the lender for a current payoff figure, since the loan balance can change over time.
Keep the lender’s payoff confirmation and the signed transfer paperwork until the loan account is settled.
How Do You Compare Used Car Dealers?
Used car dealers near you are easier to compare when you match the vehicles’ mileage, history, and written listing details. Specific details make a stronger basis for comparison than photos alone.
Compare the VIN, written price, mileage, and condition for each vehicle you are considering. Used car dealerships near you may carry different makes and inventory, so check the actual vehicle rather than relying only on a listing image.
Search nearby inventory and narrow your choices
Start with the type of vehicle that fits your daily needs, then compare models with similar mileage and features. A dealership may have a broad selection, while another may focus on certain makes or vehicle types.
Look for a written price and details about trim, equipment, and mileage. If an online listing leaves out a feature that matters to you, note it before comparing the vehicle with another one.
Save the listing details for each car so you can compare the same facts across dealerships. This also helps you spot when two vehicles have different features despite similar photos.
Check the vehicle history and listing details
Dealers covered by the Federal Trade Commission’s Used Car Rule must display a Buyers Guide on used vehicles offered for sale. The guide says whether the vehicle comes with a warranty or is sold as-is, and it points you to the written terms.
The National Motor Vehicle Title Information System, or NMVTIS, can provide title-brand, odometer, and salvage information. Use that history check as a separate step from reading the Buyers Guide.
A history report can reveal recorded events, but it does not confirm the vehicle’s current mechanical condition. Pair it with an inspection by a qualified mechanic when you need a closer look.
Photos can make a car look clean, yet they cannot show every mark or past repair. Compare the specific VIN and the dealer’s written condition details before you decide which vehicles deserve a closer look.
Save the VIN and the written condition details for each vehicle you plan to compare.
Which Fees Belong in the Vehicle’s Out-the-Door Price?
The out-the-door price includes more than the vehicle’s advertised price, so ask for an itemized total before you compare offers. The full figure helps you see what you would owe to complete the purchase.
Ask for a written out-the-door price that includes taxes, title, registration, documentation fees, and dealer-installed accessories. An advertised price alone may not show every charge in the final total.
Registration fees are set by state law and are not negotiable. California and New York cap the dealer documentation fee, while other dealer charges may have different rules.
Every U.S. state has a car-dealer documentation fee. Ask the dealership to explain any charge you do not recognize, and ask whether negotiable dealer charges or accessories can be adjusted.
Taxes, title, and registration costs can differ by state and transaction. The itemized total should make clear which charges come from state requirements and which come from the dealership.
A fee may appear on a worksheet under a short label, so ask what it covers before agreeing. If an accessory is included, ask whether it is already installed and whether it can be removed from the deal.
Do not compare two vehicles using only their advertised prices. One offer may include add-ons or charges that the other listing does not show.
Check that the written buyer’s order separates the vehicle price, taxes, title, registration, documentation fee, and any accessories.
What Warranty Comes With a Pre-Owned Vehicle?
A pre-owned vehicle’s warranty can differ by program, so compare the written coverage period and mileage limit before you sign. The label alone does not tell you every term or exclusion.
CarBravo coverage is 12 months or 12,000 miles, whichever comes first; BravoBudget coverage is 30 days or 1,000 miles, whichever comes first. The coverage type also differs between these programs.
Compare CarBravo and BravoBudget coverage
A CarBravo vehicle has a Bumper-to-Bumper Limited Warranty. Its 12-month term starts when any remaining original factory warranty expires.
A BravoBudget vehicle has a Powertrain Limited Warranty for 30 days or 1,000 miles, whichever comes first. Read the warranty papers to see what parts the plan covers.
| Program or vehicle type | Warranty term | Mileage limit | Roadside assistance or courtesy transportation |
|---|---|---|---|
| CarBravo | 12 months after remaining factory warranty expires | 12,000 miles | For the applicable CarBravo warranty |
| BravoBudget | 30 days | 1,000 miles | For the applicable CarBravo warranty |
| Non-GM vehicle with service contract | Vehicle service contract term | Set by contract | For the contract term; availability may apply |
Roadside assistance lasts for the applicable CarBravo warranty or, for a non-GM vehicle, the vehicle service contract. Courtesy transportation follows the same applicable period, but depends on vehicle availability.
Check CPO and service-contract terms
A CPO vehicle is a certified pre-owned vehicle, but each maker’s program can have its own rules. Freeway Chevrolet’s Chevrolet Certified Pre-Owned vehicles undergo safety, performance, and mechanical checks. Its program includes factory warranties and roadside assistance.
That example does not set the terms for every CPO program. Compare the written coverage for the specific vehicle, including exclusions and the date coverage begins.
Ask whether the protection comes from the vehicle maker or a separate service contract. Check who handles claims, which repairs qualify, and whether the contract has a deductible.
The mileage limit and time limit work together, so coverage may end when either limit is reached. A vehicle’s age or mileage can also affect any remaining original factory warranty.
Get the warranty start date and exclusions in writing before you complete the purchase.
How Can You Make a Dealership Visit Count?
A scheduled appointment gives you time to inspect a specific vehicle and take a focused test drive. A clear plan can help you use your time well when comparing car dealerships near you.
Ask whether the vehicle will be available, and bring a valid driver’s license for the test drive. A car dealer may need time to prepare the vehicle or confirm its location.
Set up the visit around a specific vehicle
Call or message the dealership to schedule test drive time around the vehicle you want to see. Confirm the model, trim, and listing details so staff know which car to have ready.
Ask what documents or other requirements apply to your appointment. Bring any financing or trade-in papers that relate to the visit, but keep sensitive records secure.
Use the test drive to check fit and function
Adjust the seat and mirrors before moving. Check whether you can see clearly, reach the controls, and get in and out with ease.
Choose a suitable route with turns, stops, and room to accelerate safely. Listen for unusual sounds and pay attention to how the car responds during ordinary driving.
Use this five-point check during the drive:
- Warning lights
- Braking
- Steering
- Acceleration
- Parking or reversing
The National Highway Traffic Safety Administration offers a vehicle recall lookup. The Insurance Institute for Highway Safety publishes vehicle safety ratings that can add context to your choice.
Arrange an independent inspection when needed
If the vehicle’s condition remains uncertain, ask an independent mechanic to inspect it before you buy. A test drive can show how the car feels, but it cannot replace a close mechanical check.
Ask about any written exchange policy before you complete the deal. Ron Marhofer Auto Family’s pre-owned exchange policy allows 3 days or 400 miles, whichever comes first, excluding as-is vehicles and EVs.
Exchange rules can differ across dealerships and may have limits or exclusions. Read the full written policy and make sure you understand when it applies.
Use the test drive to check the vehicle’s basic function, then arrange an independent inspection when its condition is uncertain.
Confirm that the vehicle will be available for your appointment before making the trip.
What Service Can a Dealership Arrange After Purchase?
After purchase, a dealership service department can arrange routine maintenance or diagnose a repair concern. Regular care helps you follow the vehicle maker’s schedule and keep useful records.
Routine service can include oil changes, tire rotations, and brake inspections. For a repair, ask for a diagnosis and estimate before any work begins.
Plan routine maintenance
Check the owner’s manual for the maintenance schedule for your vehicle. It can list service needs by time, mileage, or driving conditions.
A dealership’s service team can help schedule the work and explain what each visit covers. Ask how long the appointment may take and whether you need to leave the vehicle.
Keep routine maintenance separate from repairs prompted by a new sound, warning light, or change in how the car drives. Those concerns may need diagnosis before a technician can estimate the repair.
Choose a repair provider for a specific job
The National Institute for Automotive Service Excellence, or ASE, offers technician certifications for specific areas of automotive service. Ask whether a technician has an ASE credential that fits the repair you need.
Before work starts, ask for a written estimate that names the parts and labor. Tell the repair team to contact you for approval if they find extra work or the cost changes.
Ask how the shop will share updates if a repair takes longer than expected. Clear communication can help you decide whether to approve a new part or another repair step.
Approve a repair estimate before work begins, and ask the team to contact you if the scope or cost changes.
Keep service receipts with the vehicle records so the maintenance history stays easy to verify.
Conclusion
A smoother purchase starts with clear numbers, a vehicle that fits your needs, and written terms you understand. Take time to compare the full cost and make sure the vehicle suits your budget and daily use.
You can contact a local dealership to discuss financing, get a trade-in estimate, or set an appointment to see a vehicle. Bring your questions, and ask for the terms in writing before you decide.
Contact a dealership today to request a financing conversation, a trade-in estimate, or an appointment to see a vehicle.
FAQ
Can I get a car loan with no credit history?
Yes, some lenders consider applications from people with no credit history, though approval and terms depend on the lender. A cosigner, proof of income, or a larger down payment may help support an application. Ask how the lender will review your application and whether the cosigner would share responsibility for the debt. Review every loan term before accepting.
Does applying to several auto lenders hurt my credit?
Rate-shopping inquiries made within a short window are often grouped for credit scoring, but the window varies by scoring model and may be 14-45 days. Applying close together can make it easier to compare offers within that period. A lender may still review your credit as part of its application process. Ask which credit bureau it uses and when it plans to check your report.
Can I trade in a vehicle that still has a loan?
Yes, you can trade in a vehicle with a loan, but compare the payoff with the trade-in offer first. Positive equity can reduce the amount you need to finance for your next vehicle. If the payoff is higher than the offer, the difference is negative equity, which you must pay separately or add to the new loan. Ask the lender for the current payoff amount.
Is a used-car history report enough to judge a vehicle?
No, a used-car history report cannot confirm a vehicle’s current mechanical condition. It may show recorded title, mileage, or damage details, but it cannot replace a hands-on check. Pair the report with an independent mechanical inspection, especially if you have concerns about the vehicle’s condition. Ask the mechanic to explain any repairs that may need attention soon.
Can I return a used car after buying it?
There is no general federal cooling-off period for a vehicle bought at a dealer’s regular place of business. State law and the dealership’s written return or exchange policy may affect your options. Read that policy before signing, including its time limit, mileage limit, and exclusions. Keep a copy of the final paperwork so you can check the terms later.
Do I have to service my vehicle at the dealership to keep its warranty?
No, routine maintenance does not generally have to be done at the dealership to keep a warranty. Follow the owner’s manual and keep receipts that show the work and dates. The written warranty still controls what parts and repairs it covers. If you use an independent shop, ask for an itemized record and keep it with the vehicle documents.
What should I bring to a dealership appointment?
Bring a valid driver’s license if you plan to test drive a vehicle, plus any financing or trade-in documents relevant to the visit. Call ahead to confirm whether the dealership needs anything else for your appointment. You may want to bring your questions and notes about the vehicle, too. Keep personal records secure and share them only through the dealership’s approved process.



